Did you know that the monthly premium for serious illness protection can nearly double if you wait just ten years to organise your policy? It’s a sobering thought, but one that highlights the importance of proactive planning. Whether you’re confused by the differences between various protection types or anxious about the average cost of critical illness cover, it’s completely understandable to feel a bit overwhelmed by the options available to you.
We’re here to help you move past the confusion and the fear of hidden fine print. Discover how CRITICAL ILLNESS INSURANCE provides a vital financial safety net, ensuring your family remains secure whilst you focus on what truly matters: your recovery. By the end of this guide, you’ll have a clear understanding of how tax-free benefit payouts work and the confidence to choose a policy with the right conditions for your unique lifestyle. We’ll explore how to safeguard your future and ensure your financial stability remains unshakable, no matter what challenges life brings your way.
Key Takeaways
- Learn why CRITICAL ILLNESS INSURANCE provides a tax-free lump sum; it’s a vital layer of security that differs significantly from the death benefits of standard LIFE INSURANCE.
- Gain clarity on the ‘Big Three’ conditions, cancer, heart attack, and stroke, and understand how specific survival periods influence your eligibility for a full benefit payout.
- Discover how factors like your age and smoker status influence the average cost of critical illness cover, helping you to budget effectively for long-term protection.
- Distinguish between the immediate relief of a tax-free lump sum and the regular monthly support provided by INCOME PROTECTION to build a truly robust financial safety net.
- Understand the value of professional guidance when navigating complex policy definitions and comparing a wide panel of domestic providers to ensure a seamless application.
Defining the Essentials of CRITICAL ILLNESS INSURANCE
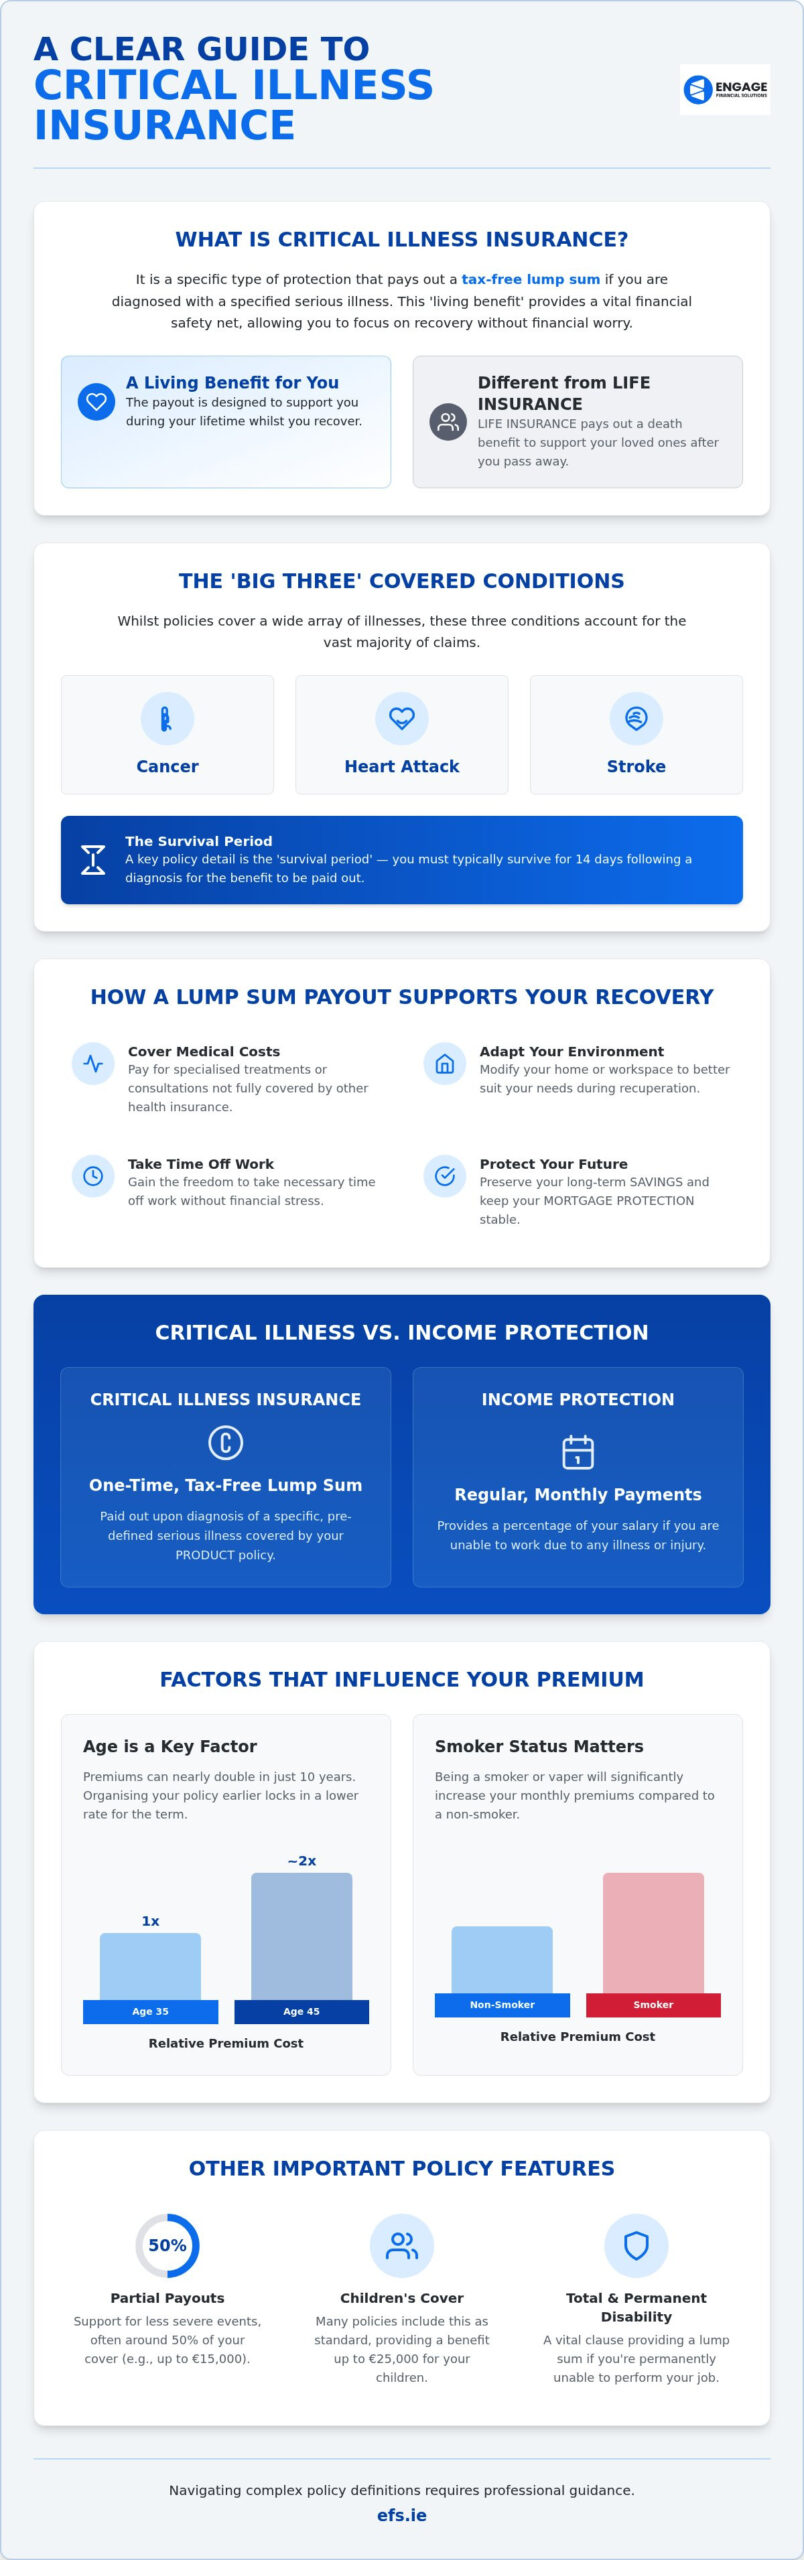
Organising your financial future involves more than just managing daily expenses; it’s about safeguarding your lifestyle against the unexpected. CRITICAL ILLNESS INSURANCE serves as a vital component of this strategy, providing a tax-free lump sum payment upon the diagnosis of a specified condition. Unlike standard LIFE INSURANCE, which is designed to support your loved ones after you pass away, this protection is for you. It’s a living benefit that offers financial liquidity when you’re facing a health challenge, allowing you to focus entirely on your recovery without the weight of mounting bills. Understanding What is Critical Illness Insurance? helps clarify why many consider it a cornerstone of a robust financial plan.
When you’re looking into the average cost of critical illness cover, it’s helpful to view the premium as an investment in your future stability. This specific PRODUCT acts as a buffer between you and the complexities of medical costs. It ensures that a health setback doesn’t become a financial crisis, providing a seamless transition from work to recovery. By securing this cover early, you’re not just buying a policy; you’re ensuring that your path toward long-term goals remains clear, regardless of what life brings your way.
How the Lump Sum Benefit Supports Your Recovery
The flexibility of a lump sum payout is one of its greatest strengths. You might use the funds to cover specialised medical treatments or consultations that aren’t fully met by your health insurance. In some cases, you may need to modify your home or workspace to better suit your needs whilst you get back on your feet. Most importantly, this capital injection gives you the freedom to take necessary time off work. You won’t have to worry about how the mortgage will be paid or how the groceries will be bought, as the payout provides the breathing room required for a steady recuperation.
The Role of Protection in Long-Term Financial Security
A serious illness can often lead to the depletion of long-term SAVINGS or pension pots, as families scramble to cover immediate costs. By having CRITICAL ILLNESS INSURANCE in place, you protect those hard-earned assets for their intended purpose. Whether you’re a first-time buyer or planning for retirement, this cover ensures your MORTGAGE PROTECTION remains stable and your family’s future lifestyle is preserved. It’s about maintaining your trajectory toward your goals, even when life takes an unexpected turn. At Engage Financial Solutions, we believe that tailored protection is the key to lasting peace of mind.
Covered Conditions and the Claim Process Explained
While every policy is unique, most domestic providers focus on what are often called the ‘Big Three’ conditions: cancer, heart attack, and stroke. These conditions account for the vast majority of claims filed today. Beyond these primary concerns, modern policies incorporate a wide array of other specified illnesses, including ‘Total and Permanent Disability’. This specific clause is vital; it provides a lump sum if you’re permanently unable to perform your job or basic daily tasks due to an illness or injury. As medical science advances, the definitions within these PRODUCT policies are regularly updated to reflect modern diagnostic standards, ensuring your cover remains effective whilst you navigate life’s transitions.
A key element of any policy is the survival period. This refers to the specific timeframe, typically 14 days, that you must survive following a diagnosis before the benefit is paid. This period is a standard feature amongst local insurers and is a crucial detail to verify when choosing your plan. When evaluating the average cost of critical illness cover Ireland, keep in mind that more expansive lists of covered conditions or more lenient survival periods can affect your monthly premiums. For those seeking a global perspective on how these plans are structured, the Forbes Advisor on Critical Illness Insurance offers excellent insights into industry norms.
Standard Conditions vs. Comprehensive Coverage
Distinguishing between ‘full’ and ‘partial’ payouts is essential. Some conditions might not meet the threshold for a total payout but still qualify for a partial payment, often around 50% of your cover or capped at €15,000. This flexibility ensures you still receive support for less severe medical events. Additionally, many policies include children’s cover as a standard feature. This typically provides a benefit of up to €25,000 or half of your total cover amount for your children, ensuring that your entire household is safeguarded against the unexpected.
Navigating the Claim Process with Ease
The goal of the claim process is to be as straightforward as possible. You’ll need to submit medical evidence from your treating consultant to confirm the diagnosis meets the policy’s specific criteria. Once the survival period is met and the paperwork is processed, the lump sum is delivered to provide immediate financial relief. Partnering with a ‘Trusted Advisor’ can make this experience much smoother, as they can help you navigate the fine print and ensure all documentation is meticulous. If you’re ready to explore your options, organising your protection with expert guidance can provide that essential peace of mind.
Comparing CRITICAL ILLNESS INSURANCE and INCOME PROTECTION
Choosing between these two forms of security often comes down to your specific financial priorities and the nature of the risks you wish to mitigate. While CRITICAL ILLNESS INSURANCE provides a one-off tax-free lump sum upon diagnosis, INCOME PROTECTION offers a regular monthly payment if you’re unable to work due to any illness or injury. The tax treatment differs significantly between the two. Payouts from serious illness cover are currently tax-free, whereas income replacement is treated as taxable income. However, a significant benefit of INCOME PROTECTION is that you can often claim tax relief on the premiums at your highest rate of tax. If you want to dive deeper into the monthly model, you can read our detailed guide on INCOME PROTECTION.
Your career stage and current debt levels play a major role in which PRODUCT you might prioritise. For someone with a large mortgage or young children, the immediate capital of a tax-free payout is often the primary concern to ensure the family home remains secure. Conversely, if you’re a self-employed professional looking to maintain a specific standard of living over many years of potential recovery, the steady stream of a monthly benefit becomes a vital lifeline. When researching the average cost of critical illness cover Ireland, it’s helpful to consider how either option fits into your wider budget for long-term security and which one addresses your most immediate fears.
The Strategic Advantage of a Lump Sum
If you have high fixed costs, such as a substantial mortgage or personal loans, the lump sum payout offers a strategic advantage that monthly payments simply cannot match. This capital injection allows you to clear debt instantly, removing a massive source of stress whilst you focus on getting better. It also provides the flexibility to make major lifestyle adjustments, such as home modifications or seeking private medical care, without waiting for monthly instalments to accumulate. You might choose this if your primary goal is the peace of mind that comes from knowing your biggest financial liabilities are handled in one go.
Can You Hold Both Policies Simultaneously?
Many people opt for a ‘Belt and Braces’ approach by holding both policies simultaneously to create a truly seamless safety net. This holistic strategy ensures that you have a significant lump sum for immediate, large-scale expenses whilst also securing a reliable income to cover your day-to-day bills and lifestyle. These two PRODUCTS complement each other perfectly, addressing different aspects of financial vulnerability. By tailoring your coverage in this way, you ensure that no single health event can derail your family’s future or your long-term aspirations, providing a level of stability that a single policy might not achieve alone.
Factors That Influence Your CRITICAL ILLNESS INSURANCE Premium
Understanding what drives your monthly premium is the first step toward making an informed decision. While you might be curious about the average cost of critical illness cover Ireland, it’s vital to remember that quotes are highly personalised. Age is perhaps the most significant factor; for example, industry data indicates that premiums for serious illness protection can double between the ages of 30 and 40. Your general health and family medical history are also evaluated to determine the level of risk. Smoker status is another major variable, as non-smokers typically enjoy much lower rates due to the reduced risk of specified illnesses like cancer or heart disease.
The structure of your cover also dictates the price. You can choose between level term cover, where the payout remains the same throughout the policy, or decreasing term cover, which is often used alongside a mortgage. Decreasing cover is generally more affordable because the potential benefit reduces over time. Additionally, your occupation is considered; if you work in a high-risk environment, providers may adjust their rates accordingly. These factors ensure that your policy is tailored to your specific life stage and risk profile, providing a fair balance between cost and security.
Managing Costs Whilst Maintaining Quality Cover
Starting your policy as early as possible is the most effective way to lock in lower rates for the long term. You’ll also need to decide between guaranteed and reviewable premiums. Guaranteed premiums remain fixed for the life of the policy, providing total certainty, whilst reviewable premiums may start lower but can be adjusted by the insurer later. A helpful tip is to review your cover whenever you hit a major financial milestone, such as a new home or a growing family, to ensure your protection still fits your needs. This proactive approach ensures you’re never paying for cover you don’t need or leaving yourself under-protected.
Supplementing Your Employer’s GROUP PROTECTION
Many professionals rely solely on ‘Death in Service’ or group illness schemes provided by their workplace. While these are valuable benefits, they often have limitations, such as lower payout caps or a restricted list of covered conditions. There’s also the significant risk that you’ll lose this cover if you change careers or leave your current role. Owning a personal policy ensures continuous stability and puts you in control of your financial safety net. It acts as a buffer that stays with you, regardless of your employment status. If you’re unsure how your current benefits stack up, contact a trusted advisor to help you identify and bridge any gaps in your protection.
Organising Your CRITICAL ILLNESS INSURANCE with Professional Guidance
Organising your financial security shouldn’t feel like a solitary burden. By partnering with a regulated consultancy, you gain immediate access to a wider panel of domestic providers than you would by approaching an insurer directly. This breadth of choice is vital when you’re looking to understand the average cost of critical illness cover Ireland for your specific age and health profile. A ‘Trusted Advisor’ serves as your steady guide, meticulously interpreting complex policy definitions and ensuring that the fine print works for you, not against you, during a claim. This professional stewardship removes the friction from the application process, allowing you to move forward with absolute confidence.
Effective protection is most powerful when it’s integrated into a holistic financial strategy. Your CRITICAL ILLNESS INSURANCE shouldn’t exist in isolation; instead, it should complement your broader RETIREMENT PLANNING and long-term SAVINGS goals. By viewing your protection through this big-picture lens, you ensure that a sudden health challenge doesn’t deplete the assets you’ve worked so hard to build. You can discover how our financial planning services protect your future by aligning your protection needs with your lifelong aspirations for stability and success.
The Personalised Approach to Protection
Generic, one-size-fits-all policies often fail to provide the necessary support when a claim is actually made. Whether you’re concerned about high fixed debts or the future education costs for your children, your cover must be tailored to your specific family needs. We take the time to understand your unique circumstances, helping you move from a state of financial anxiety to one of calm competence. This personalised attention ensures that every Euro of your premium is working to safeguard the lifestyle you’ve built for your loved ones.
Next Steps to Securing Your Peace of Mind
Your journey toward long-term security begins with a straightforward initial consultation. During this review, we’ll examine your current level of cover and identify any potential gaps that could leave you vulnerable. We act as the proactive buffer between you and the insurance providers, handling the technical negotiations and paperwork on your behalf. This seamless experience ensures that you can focus on your career and family whilst we manage the complexities of the market. If you’re ready to find the average cost of critical illness cover Ireland that fits your budget and provides genuine peace of mind, start your journey toward a stable financial future today.
Securing a Stable Path Forward
Taking control of your financial future is one of the most empowering decisions you can make for your family. We’ve explored how CRITICAL ILLNESS INSURANCE provides a vital tax-free lump sum, ensuring that a health challenge doesn’t derail your long-term goals or deplete your hard-earned SAVINGS. Whether you’re comparing payout structures or researching the average cost of critical illness cover Ireland, the key is to move from a state of anxiety to one of calm competence through proactive and meticulous planning.
As a consultancy regulated by the Central Bank, our experienced team of financial consultants is here to act as your steady guide. We provide access to a comprehensive panel of leading domestic providers, ensuring your protection is tailored to your unique lifestyle and long-term aspirations. Don’t leave your security to chance; instead, choose a partner who simplifies the complex and removes the friction from financial transitions. Book a consultation with Engage Financial Solutions to secure your future and take the first step toward a seamless, protected tomorrow. Your peace of mind is our priority, and we’re ready to help you safeguard what matters most.
Frequently Asked Questions
Is the payout from CRITICAL ILLNESS INSURANCE taxable under local rules?
No, the payout from CRITICAL ILLNESS INSURANCE is currently paid as a tax-free lump sum under domestic tax regulations. This is a significant advantage compared to other forms of protection that might be subject to income tax. Because the benefit is delivered in one go, you can use the entire amount to manage your recovery or clear debts without a tax bill. It’s always wise to confirm the latest revenue guidelines during your consultation.
Can I get cover if I have a pre-existing medical condition?
Whether you can obtain cover depends on the nature and severity of your condition. While pre-existing conditions are generally excluded from new policies, many providers will still offer cover for unrelated illnesses. During the application process, you’ll provide a full medical history to the insurer. A trusted advisor can help you navigate this by identifying providers who are more flexible or offer tailored terms based on your specific health profile and previous medical history.
What is the difference between serious illness cover and MORTGAGE PROTECTION?
MORTGAGE PROTECTION is specifically designed to pay off your remaining loan balance to the lender if you pass away. In contrast, CRITICAL ILLNESS INSURANCE pays a lump sum directly to you upon diagnosis of a covered condition. While you can add serious illness cover to a mortgage policy, the primary difference lies in who receives the funds and how they are used. One secures your home for your family, whilst the other provides personal financial liquidity.
How much CRITICAL ILLNESS INSURANCE do I actually need for my family?
The amount you need depends on your specific financial liabilities, such as your mortgage balance, outstanding loans, and your family’s annual living expenses. Many experts suggest a sum that covers at least two years of your net income plus any major debts. When considering the average cost of critical illness cover Ireland, it’s important to balance the premium with a benefit amount that truly provides peace of mind. We help you calculate a figure that safeguards your future.
Does this insurance cover me for mental health conditions?
Standard CRITICAL ILLNESS INSURANCE policies typically don’t cover most mental health conditions, as they focus on specified physical illnesses like cancer or stroke. However, some comprehensive plans may include benefits for very specific, severe neurological conditions or ‘Total and Permanent Disability’ that prevents you from working. It’s essential to review the specific definitions within your policy document. If mental health support is a priority, you might also consider how INCOME PROTECTION fits into your broader financial plan.
What happens if I never make a claim on my policy?
If you reach the end of your policy term without making a claim, the cover simply expires and there is no payout or return of premiums. This PRODUCT is designed as a safety net rather than a savings vehicle. Think of it like car insurance; you pay for the security of knowing the support is there if the worst happens. Some policies offer a ‘conversion option’ which allows you to start a new policy without further medical evidence before the old one ends.
Can I cancel my policy if my financial circumstances change?
Yes, you have the flexibility to cancel your policy at any time if your circumstances change. There is usually no penalty for doing so, but it’s important to remember that your cover will cease immediately. If you decide to take out cover again later, the average cost of critical illness cover Ireland will likely be higher because you’ll be older. We recommend reviewing your needs with a consultant before cancelling to ensure you aren’t leaving yourself or your family vulnerable.
How long does a typical policy last?
Most policies are organised to last until a specific milestone, such as your retirement age or the date your mortgage is paid off. This typically ranges between 10 and 40 years. You can choose a term that aligns with your most significant financial responsibilities. Many people opt for cover until age 65 or 70 to ensure they’re protected during their primary earning years, providing stability during the most critical stages of their professional lives.
Disclaimer
Engage Financial Services LTD T/A Engage Financial Solutions is regulated by the Central Bank of Ireland CRO 764570. Suite 2 First Floor, 14 -18 Main street, Blackrock, Co Dublin. A94 W0Y3