What if the most effective way to lower your monthly bills wasn’t by turning down the heating, but by changing how you pay for your home? You’ve likely noticed the rising cost of living and those ever-climbing energy statements that arrive in the post. It’s a common source of stress, especially when you’re trying to balance a household budget against fluctuating market rates. Whether you’re purchasing your first property or considering SWITCHING MORTGAGES for an existing home, finding a path to long-term stability is a vital step towards a more secure future.
By choosing a GREEN MORTGAGE, you can unlock significantly lower interest rates and safeguard your financial future through sustainable choices. This guide explains how to qualify for these specialised products and demonstrates how a higher BER rating translates into immediate, tangible monthly savings. We will walk you through the application process, explain the technical requirements in plain English, and show you how a more energy-efficient home leads to a more seamless path towards financial security and peace of mind.
Key Takeaways
- Discover how a GREEN MORTGAGE rewards energy efficiency with lower interest rates, helping you reduce monthly outgoings whilst supporting a more sustainable future.
- Learn why a Building Energy Rating (BER) of B3 or higher is typically the essential threshold for accessing these preferential financial products.
- Explore how GREEN MORTGAGES Ireland can provide long-term financial stability by lowering your total borrowing costs compared to standard fixed rates.
- Identify the specific steps required for a seamless application, including how to verify your property’s eligibility and secure a valid certificate.
- Understand the big-picture benefits of SWITCHING MORTGAGES to a more efficient product to enhance both your home’s value and your long-term financial security.
What Is a GREEN MORTGAGE and How Does It Benefit You?
A GREEN MORTGAGE is a financial reward for owning a home with a high energy performance rating. You’ve likely heard the term mentioned in property circles; it’s much more than just a buzzword. Essentially, a GREEN MORTGAGE is a specialised home loan that offers you a lower interest rate in exchange for living in an energy-efficient property. When you choose a green mortgage, you’re tapping into a system that rewards sustainability with tangible financial savings.
Lenders aren’t just doing this out of goodwill. They provide these incentives to support national sustainability goals and reduce their own credit risk. A home that costs less to heat and light is a property where the owner is less likely to face financial strain, making you a more reliable borrower in the eyes of the bank. When researching green mortgages Ireland, you’ll find that these products typically require a Building Energy Rating (BER) of B3 or better. By selecting from the available green mortgages Ireland, you can enjoy reduced monthly repayments and the potential for increased property value over time.
The Link Between Energy Efficiency and Lower Rates
There’s a logical connection between a warm home and a healthy bank balance. Financial institutions view energy-efficient properties as lower-risk assets because they’re cheaper to maintain. When your utility bills are lower, your disposable income is higher, which improves your overall mortgage affordability. This isn’t just about the immediate discount; it’s about building a foundation for long-term financial security. Integrating this type of PRODUCT into your broader financial plan ensures your most significant monthly outgoing remains manageable.
Who Can Apply for This PRODUCT?
You might wonder if this PRODUCT is only for those buying brand-new houses. Whilst FIRST-TIME BUYER MORTGAGES for new-builds are a common entry point, the options are much broader. Whether you’re purchasing your first home or looking to improve your current property’s efficiency, there are several paths to qualification:
- Existing Homeowners: If you’ve upgraded your current home with solar panels or better insulation, you may be eligible when SWITCHING MORTGAGES to a new lender.
- Self-Build Projects: Those embarking on a self-build can often qualify during the construction phase, provided the final plans meet the necessary efficiency criteria.
- Property Investors: Many lenders also offer these rates for buy-to-let properties with high energy ratings.
This flexibility makes it a viable option for many different life stages, ensuring you feel looked after regardless of your specific circumstances.
BER Ratings Explained: The Gateway to Better Rates
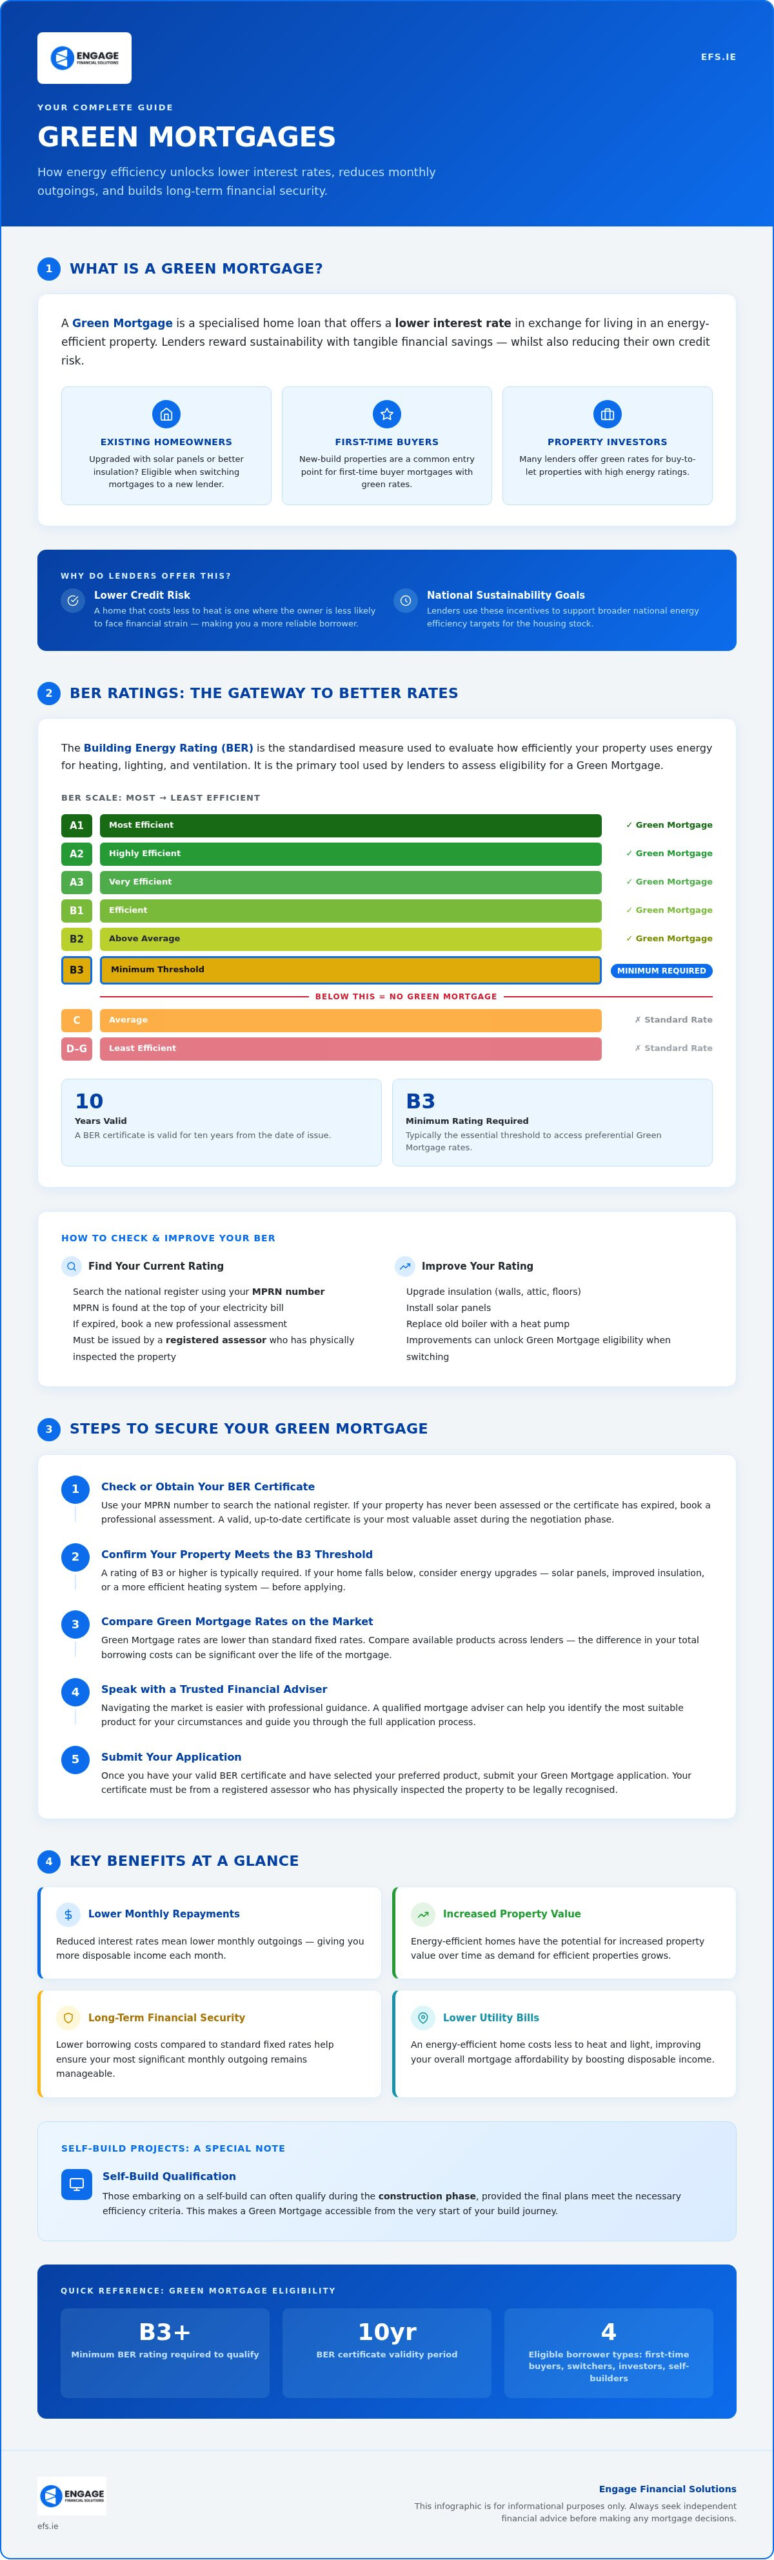
Understanding your home’s energy performance is the first step towards securing a better rate. The Building Energy Rating, or BER, is the standardised measure used to evaluate how efficiently your property uses energy for heating, lighting, and ventilation. It’s essentially an efficiency label for your house, with a scale ranging from A1, representing the most efficient homes, down to G for the least efficient. This rating isn’t just about environmental impact; it’s the primary tool used by lenders when you’re comparing mortgage rates to see if you qualify for a discount.
Most lenders now require a minimum rating of B3 to unlock the benefits of a GREEN MORTGAGE. This threshold ensures that the property meets modern efficiency standards, which in turn reduces the risk for the financial institution. It’s important to remember that a BER certificate is valid for ten years from the date of issue. To be legally recognised for a mortgage application, it must be issued by a registered assessor who has physically inspected the property. When researching green mortgages Ireland, having a valid and up-to-date certificate is your most valuable asset during the negotiation phase.
How to Check Your Current BER
If you aren’t sure of your home’s current status, you can easily find your existing certificate on the national register using your MPRN number. This number is usually found at the top of your electricity bill. If your property has never been assessed, or if the certificate has expired, you’ll need to book a professional assessment. The cost typically varies depending on the size and type of the home. It’s a straightforward process that provides you with a detailed report on your property’s performance and potential for improvement.
Improving Your Rating to Qualify
Upgrading your home doesn’t just make it more comfortable; it’s a strategic move to lower your borrowing costs. Practical steps like increasing attic insulation, installing a heat pump, or upgrading to triple-glazed windows can significantly boost your score. Even smaller changes, such as professional draught-proofing or installing more efficient heating controls, contribute to a better final result. These improvements help you move closer to that B3 target, making the prospect of SWITCHING MORTGAGES to a more affordable rate much more attainable.
A vital step in this journey is to always get a “post-works” BER assessment once your upgrades are complete. This updated document serves as your official proof of eligibility, allowing you to demonstrate your home’s improved performance to your lender. By taking a proactive approach to your home’s efficiency, you’re not just saving on bills; you’re actively safeguarding your long-term financial stability.
Analysing the Savings: GREEN MORTGAGE vs Traditional Fixed Rates
When you look at the numbers, the true value of green mortgages becomes clear. It isn’t just about environmental responsibility; it’s a calculated move to improve your household’s bottom line. Most lenders offer a rate discount for energy-efficient homes, which typically ranges from 0.1% to 0.5% below their standard fixed rates. This reduction might seem modest at first glance, but it compounds over time to create substantial relief. Even a 0.2% rate difference can save thousands over the life of a loan.
Cashback offers also play a significant role in this transition. Many institutions provide a lump sum upon completion, which you can use to offset the initial costs of moving your loan or perhaps to fund further energy upgrades. Whilst these offers are attractive, it’s vital to look at the long-term interest rate rather than just the immediate windfall. A lower rate provides ongoing security, whereas a one-off payment is a short-term benefit that quickly fades. Evaluating these options with a steady guide ensures you choose the path that best supports your long-term financial health.
The Financial Impact of a SWITCHING MORTGAGE
Moving your current loan to a more efficient rate can significantly accelerate your path to being debt-free. Consider a homeowner with a €300,000 balance who improves their property’s BER from a D rating to a B rating. By learning more about the benefits of a SWITCHING MORTGAGE, they might secure a green rate that is 0.35% lower than their previous product. Over a five-year fixed term, this single decision could result in interest savings of over €5,000. This is money that stays in your pocket, providing extra flexibility for your lifestyle, your pension, or future investments.
Hidden Costs to Consider When You Switch
Whilst the savings are compelling, you must budget for the practicalities of the transition to ensure the process remains straightforward. You’ll typically need to account for legal fees, which often range between €1,000 and €1,500 plus VAT, and a professional valuation report costing approximately €150. If you’re currently on a fixed-rate contract, you should also check for any “break fees” that might apply for ending the term early. However, when you view these through a “future-back” lens, the long-term interest savings almost always outweigh these upfront expenses. A proactive approach allows you to manage these costs without stress, leading to a more stable and optimistic financial outcome.
Actionable Steps to Secure Your GREEN MORTGAGE
Securing a lower interest rate through energy efficiency requires a methodical and proactive approach. It isn’t merely about the property’s performance; it’s about demonstrating your readiness as a borrower to ensure a seamless transition. By following a structured path, you can remove the friction often associated with financial applications and move towards a more secure future with confidence. When exploring the various green mortgages Ireland has available, preparation is your most effective tool for success.
Your journey begins with a comprehensive financial review to assess your current borrowing capacity. This allows you to understand exactly how much you can borrow before you commit to any specific PRODUCT. Once your budget is clear, the next step is to obtain a valid BER certificate. This document confirms your property meets the necessary criteria for a discounted rate. Following this, you should organise your documentation, consult with a professional advisor to compare every available option, and finally submit your application while managing the valuation process with expert guidance.
Documentation Checklist for a Smooth Application
Having your paperwork in order from the outset prevents unnecessary delays. Whilst the core requirements are similar for everyone, there are specific differences depending on your employment status. PAYE employees should gather their three most recent payslips and their latest Employment Detail Summary, which has replaced the traditional P60. Conversely, self-employed individuals typically need to provide two years of certified accounts and tax clearance confirmation. Regardless of your status, the BER certificate remains the most critical document for this specific PRODUCT, as it serves as the official proof of your home’s efficiency.
One actionable tip to remember is to ensure your bank statements are “clean” for at least six months before you apply. Lenders look for consistent financial behaviour, so avoiding overdraft usage or large, unexplained transactions during this period will make your application much stronger. If you are ready to begin gathering your documents, you can start your journey with Engage Financial Solutions today.
Timing Your Move: When to Start the Process
Timing is essential to ensure you don’t spend a single day on a higher standard variable rate. If you are currently on a fixed-rate contract, it’s wise to start the switching process approximately four to six months before your term expires. This provides ample time to navigate the valuation and legal stages without feeling rushed. Securing one of the many green mortgages Ireland provides depends on your ability to prove your home’s efficiency at the right moment, as most offers remain valid for six months once issued.
If you are currently undertaking energy upgrade works, such as installing a heat pump or upgrading insulation, coordination is key. You must ensure that your “post-works” BER assessment is completed and the certificate is issued before the final loan offer is processed. Aligning these milestones ensures that your home’s improved performance is officially recognised, allowing you to lock in the best possible rate for your long-term stability.
Navigating the Market with a Trusted Financial Advisor
Selecting the right path through a complex financial landscape requires more than just a search engine; it requires a partnership with a steady guide. Whilst you now understand the technical requirements and the potential for savings, the actual market contains dozens of lenders, each with their own unique criteria. A professional advisor acts as your steward, navigating these options to find the specific PRODUCT that aligns with your lifestyle and long-term aspirations. Our goal is to ensure that your journey toward securing green mortgages Ireland is not just successful, but entirely seamless.
The value of expert guidance lies in the ability to see the big picture. We don’t simply look at a single interest rate; we examine how a GREEN MORTGAGE fits into your overall financial health. By anticipating potential stresses and neutralizing them before they occur, a dedicated consultant provides the calm competence you need during a major financial transition. This proactive approach ensures that every detail, from the initial BER verification to the final loan offer, is handled with meticulous attention.
Why a Bespoke Approach Beats a Standard Bank Meeting
Meeting with a single bank provides a narrow view of what’s possible. An independent broker has access to a wide panel of lenders, allowing you to compare multiple rates simultaneously to ensure you secure the absolute lowest option for your BER rating. We often have access to specialised, broker-only products that aren’t available directly to the public, providing an additional layer of value and potential savings. Our role is to act as a buffer, translating complex requirements into straightforward steps and handling the meticulous details. This removes the friction from the process, allowing you to focus on the optimism of your new home or the relief of your reduced monthly bills.
Securing Your Future Success
A GREEN MORTGAGE is just one piece of your financial puzzle. To achieve true peace of mind, it’s essential to integrate your home loan with other vital protections, such as MORTGAGE PROTECTION and LIFE INSURANCE. By tailoring your repayments to fit your specific budget, we ensure you maintain the capacity for continued SAVINGS AND INVESTMENTS. This holistic approach means your financial decisions today are actively building the security you desire for your retirement and long-term goals. We don’t just help with the initial loan drawdown; we provide ongoing support to ensure your plan remains robust as your life evolves. Contact Engage Financial Solutions today for a personalised review of your options and take the first step towards a more stable future.
Secure Your Sustainable Financial Future
Choosing a more energy-efficient path for your home is one of the most rewarding financial decisions you can make. By understanding the link between your property’s performance and your interest rate, you’ve taken the first step toward significant long-term savings. Whether you’re a first-time buyer or looking at the benefits of a SWITCHING MORTGAGE, the transition to a more sustainable product offers both immediate relief and future security. Navigating the variety of green mortgages Ireland offers becomes a straightforward process when you have a steady guide by your side.
Our team provides bespoke guidance across a wide panel of lenders, ensuring your home loan is tailored to your unique financial goals. As a firm regulated by the Central Bank, we prioritise your peace of mind and handle the meticulous details of your application to ensure a seamless experience. Book a consultation with our expert team to find your perfect GREEN MORTGAGE and start your journey toward a more stable and optimistic future today. You don’t have to navigate these complex transitions alone; we’re here to protect your interests every step of the way.
Frequently Asked Questions
What BER rating do I need for a GREEN MORTGAGE?
You generally need a Building Energy Rating (BER) of B3 or higher to qualify for this type of PRODUCT. Most lenders set this as the minimum standard for green mortgages Ireland because it represents a high level of energy efficiency. If your home is rated between A1 and B3, you can access these lower interest rates. If your rating is lower, you might consider energy upgrades to reach this threshold before applying.
Can I get a GREEN MORTGAGE if I am switching from another lender?
Yes, you can certainly access this PRODUCT when SWITCHING MORTGAGES from another lender. If your current home already meets the required energy standards, or if you have recently completed upgrades that improved your rating to B3 or better, you can move your loan to a more competitive rate. This process is a straightforward way to reduce your monthly repayments whilst improving your long-term financial stability and security.
Is a GREEN MORTGAGE always the cheapest option on the market?
Whilst this PRODUCT often offers the most competitive rates, it isn’t guaranteed to be the cheapest for every single borrower. Factors such as your Loan-to-Value (LTV) ratio and the specific terms offered by different lenders on their standard products can influence the final cost. However, for those with a high-efficiency home, green mortgages Ireland typically provide significant savings compared to traditional fixed rates. It’s always wise to compare the entire market with an advisor.
What documents are required for a GREEN MORTGAGE application?
You will need to provide several key documents, with the most important being a valid BER certificate issued by a registered assessor. In addition to this, standard requirements for any home loan application apply. These include proof of income, such as recent payslips or certified accounts, and six months of clear bank statements. Having these organised in advance ensures a more seamless and stress-free application process for your chosen PRODUCT.
How long does a GREEN MORTGAGE fixed rate usually last?
Most lenders offer these specialised rates on fixed terms that typically range from two to ten years. A five-year fixed term is a very common choice for many homeowners as it strikes a balance between immediate savings and medium-term security. Choosing the right term depends on your personal circumstances and whether you value flexibility or long-term stability more highly. Your advisor can help you select a duration that fits your wider financial plan.
Can self-build projects qualify for a GREEN MORTGAGE during construction?
Yes, self-build projects can qualify for this PRODUCT, provided the final construction plans meet the B3 energy rating threshold or higher. Lenders often allow you to lock in a green rate during the construction phase based on your projected energy performance. Once the build is finished, you’ll need to provide a final BER certificate to confirm the property meets the agreed standards. This ensures your new home is efficient and affordable from day one.
Do I need to pay for a new BER assessment if I already have one?
You only need a new assessment if your current certificate is more than ten years old or if you have made significant energy improvements to your home. If you’ve recently installed solar panels, triple glazing, or a heat pump, a new assessment is vital to prove your improved rating to the lender. This updated document is the primary evidence required to unlock the lower interest rates associated with green mortgages Ireland and maximise your savings.
What happens to my GREEN MORTGAGE rate if my BER rating expires?
Your current interest rate typically remains unchanged for the remainder of your fixed-rate term, even if the certificate expires during that period. However, when your fixed term ends and you look to re-fix or switch to a new PRODUCT, you will need a valid, up-to-date certificate to qualify for a green rate again. Keeping your documentation current ensures you can always access the most competitive and sustainable financial options available on the market.
Disclaimer
Engage Financial Services LTD T/A Engage Financial Solutions is regulated by the Central Bank of Ireland CRO 764570. Suite 2 First Floor, 14 -18 Main street, Blackrock, Co Dublin. A94 W0Y3