Most homeowners assume that the policy offered by their lender is a fixed, non-negotiable cost of buying a home; however, sticking with a bank-linked insurer could be costing you thousands of Euro over the lifetime of your loan. Finding the cheapest MORTGAGE PROTECTION available on the domestic market doesn’t mean you have to sacrifice the quality of your cover or the security of your family. It’s natural to feel concerned about high monthly premiums or the complexities of medical underwriting, especially when you simply want to ensure your future is secure and stable.
We’ll show you how to secure the lowest premiums on your mandatory cover whilst ensuring full protection for your home and your loved ones. This guide explores the practical steps to comparing the market effectively, ensuring a straightforward path to significant monthly savings. Whether you’re a first-time buyer or looking to switch an existing policy, you can expect a seamless process that prioritises your financial health and provides total peace of mind for the years ahead.
Key Takeaways
- Understand why MORTGAGE PROTECTION is a legal requirement and how this specialised form of LIFE INSURANCE secures your property by clearing the remaining debt.
- Learn how to find the most affordable cover by conducting a market-wide review rather than defaulting to the high premiums often offered by lending banks.
- Discover the significant impact lifestyle choices, such as smoking behaviour, have on your monthly costs and how to access the most competitive non-smoker rates.
- Identify common pitfalls like non-disclosure or under-insuring to ensure your family remains fully protected whilst maintaining low monthly outgoings.
- Explore how a professional advisor acts as a buffer between you and the insurance market, ensuring a seamless and straightforward application process.
What is MORTGAGE PROTECTION and Why is it Mandatory?
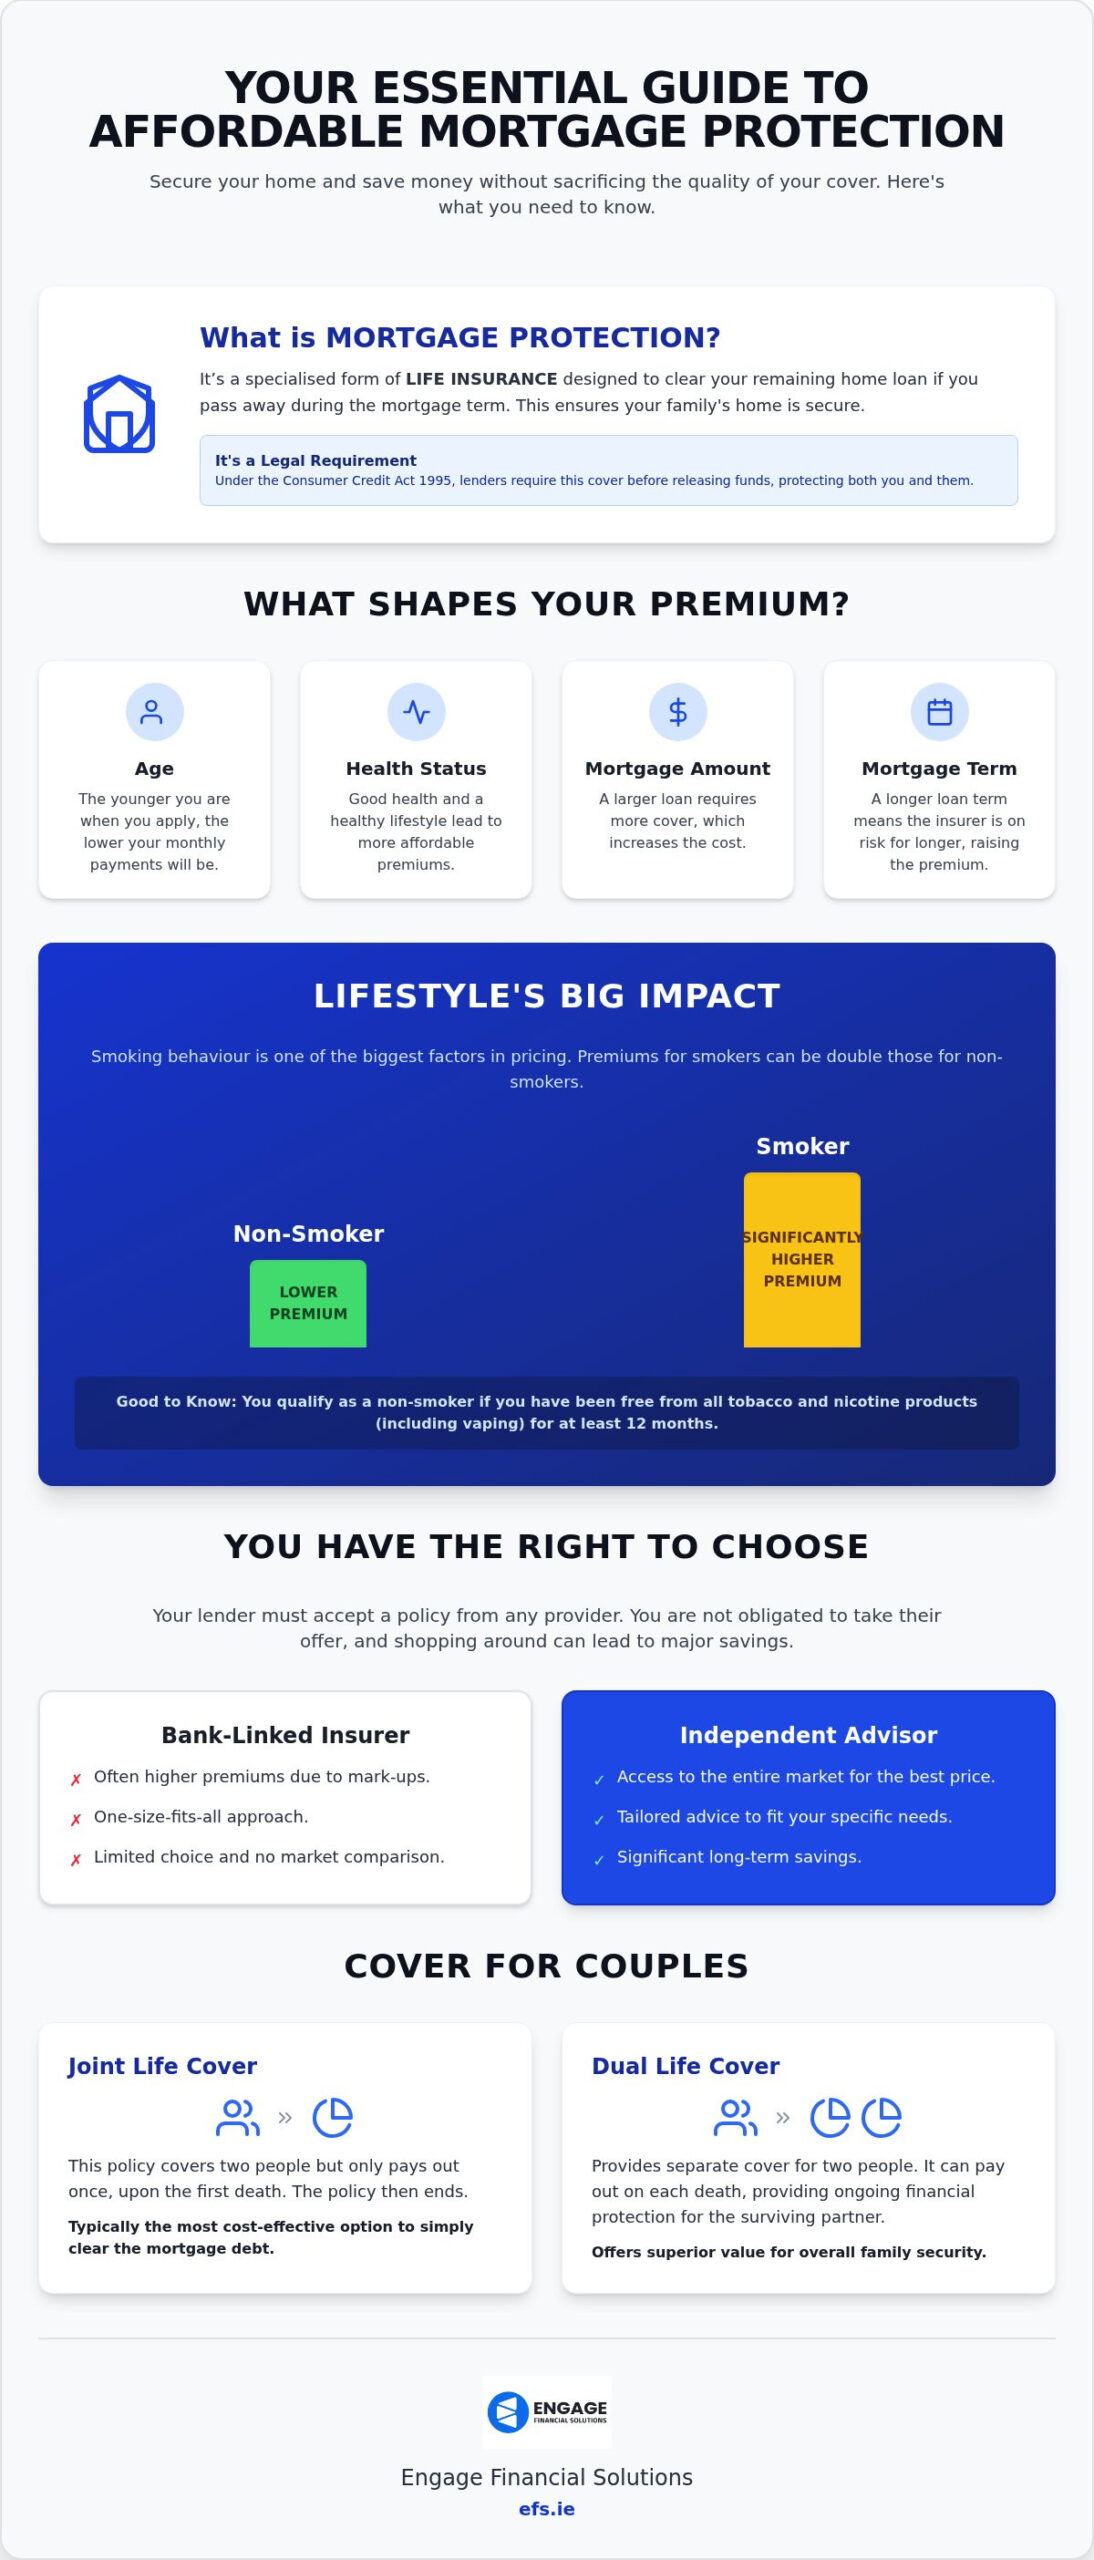
MORTGAGE PROTECTION is a specialised form of LIFE INSURANCE designed to clear your remaining home loan if you pass away during the term of the mortgage. It acts as a safety net, ensuring that your family isn’t burdened with a debt they cannot service. Unlike other forms of insurance that provide a lump sum for general use, this policy is tied directly to your property debt. As you pay off your mortgage, the amount the insurer would pay out reduces accordingly, which is why it’s often called “reducing term” cover. This design keeps the premiums lower than standard life policies, helping you secure the cheapest mortgage protection available for your circumstances.
The requirement to have this cover isn’t just a suggestion from your bank; it’s a legal obligation under the Consumer Credit Act 1995. This legislation requires lenders to ensure that a policy is in place before they release the funds for a property purchase. The goal is to protect both the lender’s interest and your family’s home. Whilst the bank must see proof of cover, they cannot dictate where you buy it. This distinction is vital for anyone looking to save money, as the market for these policies is highly competitive, and looking beyond the lender’s own offering often reveals significant savings.
The Difference Between MORTGAGE PROTECTION and LIFE INSURANCE
It’s easy to confuse these two types of cover, but understanding the difference is the first step to avoiding unnecessary costs. MORTGAGE PROTECTION is specifically for the loan; its value falls as your debt decreases. In contrast, standard LIFE INSURANCE pays out a fixed amount regardless of how much you owe on your home. If your primary goal is simply to satisfy the lender’s requirements at the lowest possible cost, the reducing term nature of a mortgage-specific policy is almost always the most efficient choice. Essentially, one protects the bank’s debt whilst the other protects your family’s lifestyle and future aspirations.
Your Right to Choose Your Own Provider
You have a legal “right to choose” when it comes to your insurance provider. Many buyers feel a sense of pressure to accept the policy bundled with their mortgage offer, but you’re under no obligation to do so. Banks are prohibited from penalising you or changing your mortgage terms if you decide to go with an independent provider. Organising your cover early in the application process prevents last-minute stress and gives you the time to compare quotes from across the domestic market. By choosing a tailored policy from a specialist like Engage Financial Solutions, you ensure you’re getting the best value without the high mark-ups often found in bank-linked products.
Factors That Determine the Cost of Your Policy
Your monthly premium isn’t a random figure; it’s a carefully calculated reflection of risk. Age and health status stand as the primary drivers of these costs. Generally, the younger and healthier you are when you apply, the lower your monthly payments will be. Lenders and insurers look at these factors to estimate the likelihood of a claim during the mortgage term. Because of this, it’s often more affordable to secure cover sooner rather than later, as premiums tend to rise with each passing year.
The specific details of your loan also dictate the starting price. A higher mortgage amount requires a larger potential payout, which naturally increases the premium. Similarly, a longer term, such as a 30-year mortgage versus a 15-year one, means the insurer provides cover for a more extended period. These variables form the foundation of your quote before any personal health details are even considered.
Smoker vs Non-Smoker Rates
Smoking behaviour has a significant impact on insurance premiums. If you’ve been tobacco-free for at least 12 months, you can often slash your premiums significantly compared to a smoker. Most insurers treat vaping exactly the same as traditional smoking, so don’t expect a discount for switching to e-cigarettes. If you’ve quit since taking out your original policy, you can declare this change in status to potentially reduce your ongoing costs. Finding the cheapest mortgage protection Ireland offers often starts with being honest about these lifestyle habits and ensuring your status is up to date.
Joint Life vs Dual Life Policies
When applying as a couple, you’ll choose between Joint Life and Dual Life cover. A Joint Life policy pays out once upon the first death and then ends. In contrast, a Dual Life policy provides separate cover for both individuals, meaning it can pay out twice. Whilst Dual Life offers superior value for family security, Joint Life is typically the more cost-effective option for a standard MORTGAGE PROTECTION requirement where the only goal is clearing the debt.
The final price you pay is determined during the medical underwriting process. This is where the insurer reviews your medical history to confirm the initial quote. If you have a pre-existing condition, the premium might be increased. Working with a specialist who understands different insurers’ appetites for certain health risks can help you navigate this stage without friction. You can chat with our team to see how we can help tailor a solution to your specific health profile and secure the most competitive rate available.
How to Secure the Cheapest MORTGAGE PROTECTION
Securing a low-cost policy is less about luck and more about the strategy you employ during the application phase. Most people default to the policy suggested by their bank because it feels like the path of least resistance during a stressful time. However, this convenience often comes at a significant premium. To find the cheapest mortgage protection Ireland has available, you must look beyond the lending institution and engage with the broader market. A bank is usually tied to a single provider, whereas an independent specialist can navigate multiple insurers to find the most competitive fit for your specific health and age profile.
The Power of Market-Wide Comparison
Relying on just one or two quotes is a common mistake that can lead to years of overpayment. Independent advisors operate with a wider perspective, accessing a panel of insurers that compete for your business. These professionals often identify specific “discounted start” programmes or “price match” guarantees that aren’t visible on standard comparison sites. If one insurer offers a lower rate for the same level of cover, a broker can often leverage that information to secure an even better deal for you. Consider the long-term impact; a saving of 10% on your monthly premium might feel small today, but over a thirty-year term, that money compounds into a substantial sum that could be better spent on your home or family.
Reviewing Cover During a MORTGAGE SWITCH
Life doesn’t stand still, and neither should your insurance. The best time to hunt for a more affordable policy is when you switch your mortgage to take advantage of better interest rates. As you pay down your debt and your loan-to-value ratio falls, you become a more attractive prospect for insurers who may have been more expensive when you were a first-time buyer. Many homeowners find that their health status or lifestyle has also improved since their initial application, providing a perfect opportunity to reset their premiums at a lower level.
At Engage Financial Solutions, we pride ourselves on being the buffer between you and the technical complexities of the insurance market. We can manage both your mortgage transition and your protection review simultaneously, creating a seamless experience that prioritises your financial health. We act as your steady guide, anticipating potential hurdles in the underwriting process and neutralizing them before they cause delays. By aligning your protection with your current mortgage balance and property value, you ensure that you aren’t paying for unnecessary cover, keeping your premiums lean and efficient for the years ahead.
Common Pitfalls to Avoid When Seeking Low-Cost Cover
The search for the cheapest mortgage protection Ireland provides often leads homeowners to prioritise price over performance. However, a policy that fails to clear your debt in a worst-case scenario is never truly a bargain. One of the most frequent errors is under-insuring, where a borrower trims the term or the sum assured to save a few Euro each month. This leaves a gap between your actual debt and the insurance payout, potentially leaving your family with a remaining balance they cannot afford to service. You should also be wary of ignoring the fine print regarding CRITICAL ILLNESS INSURANCE additions, as some “budget” versions only cover a limited range of conditions, offering a false sense of security.
The Risk of Non-Disclosure
A “cheap” policy is entirely useless if it fails to pay out when your family needs it most. Non-disclosure, or the omission of medical details during the application, is the leading cause of declined claims. You must be meticulous with your medical history; even minor details about past health issues or family history are relevant to the insurer. Professional help is invaluable here. We act as a buffer between you and the underwriters, ensuring your application is accurate and robust. This proactive approach neutralises the risk of future disputes and guarantees that the protection you pay for is legally sound.
Balancing Cost with Comprehensive Security
Focusing purely on life cover can sometimes leave other significant risks unaddressed. Whilst clearing the mortgage debt is the priority, consider how your household would function if you were unable to work due to illness or injury. For many, adding a layer of safeguarding your earnings through INCOME PROTECTION provides a more holistic level of security. You might also look for policies that include a “waiver of premium” feature. This ensures that if you’re seriously ill and cannot work, the insurer pays your premiums for you, keeping your cover active without adding to your financial strain.
Failing to review your policy when your life circumstances change is another common trap. If you’ve had children, moved to a larger home, or seen a significant salary increase, your original low-cost policy may no longer be fit for purpose. Regularly checking your cover ensures it remains aligned with your long-term aspirations. If you’re unsure if your current policy still offers the best value, speak with our expert advisors today to ensure your home remains fully protected at the most competitive rate.
How Engage Financial Solutions Simplifies Your Search
Securing the cheapest mortgage protection Ireland provides shouldn’t feel like an additional burden during your home-buying journey. We act as a dedicated buffer between you and the complexities of the insurance market, translating technical requirements into clear, actionable choices. Our team brings a sense of calm competence to every review, ensuring your path to a new home or a more competitive interest rate is entirely seamless. We don’t just look for the lowest price; we ensure your cover is meticulously tailored to your specific life stage and long-term aspirations.
Our role as your steady guide is to anticipate potential stresses in the underwriting process and neutralize them before they cause delays. By focusing on your desired end-state of financial security, we work backward to find the product that fits your lifestyle today. This goal-driven approach ensures that your protection is lean, efficient, and robust enough to stand the test of time.
Our Professional Partnership Approach
Whether you’re a first-time buyer or a seasoned homeowner looking to switch, our process begins with a personalised consultation. We take the time to understand your unique circumstances before navigating our extensive panel of insurers to find the best value. As a regulated MORTGAGE BROKER, we’re committed to your long-term success and handle the heavy lifting of paperwork on your behalf. This removes the friction often associated with insurance applications, allowing you to focus on the excitement of your new property whilst we safeguard your future.
Next Steps to Lower Your Monthly Costs
Taking control of your monthly outgoings is a straightforward process when you have the right support. We encourage you to gather your current policy details for a free, no-obligation review to see if a more cost-effective option is available in the current market. You can contact us today to begin your search for a better rate. Our expertise also extends to RETIREMENT PLANNING, providing you with a holistic view of your financial health. By integrating your MORTGAGE PROTECTION into a broader plan for stability, we help you build a foundation for lifelong success and peace of mind.
Achieve Long-Term Security and Savings
Finding the cheapest mortgage protection Ireland has to offer is a journey that moves from initial confusion to long-term financial stability. By looking beyond your lender’s standard quote and embracing a market-wide comparison, you can unlock significant monthly savings whilst maintaining the highest standards of cover for your family. Meticulous accuracy during the application process ensures that your home remains a secure sanctuary for years to come.
Our team at Engage Financial Solutions acts as your steady guide, managing the insurance market so you don’t have to. As expert advisors in MORTGAGE PROTECTION and LIFE INSURANCE, we’re regulated by the Central Bank and dedicated to providing a seamless switching process that prioritises your peace of mind. We’re here to ensure every transition is straightforward and stress-free.
Speak with a MORTGAGE BROKER at Engage Financial Solutions for a tailored quote and take the first step towards a more secure and affordable future today.
Frequently Asked Questions
Is MORTGAGE PROTECTION the same as LIFE INSURANCE?
No, they are distinct products with different purposes. MORTGAGE PROTECTION is a specific form of LIFE INSURANCE where the payout reduces over time to match your decreasing loan balance. Standard LIFE INSURANCE pays out a fixed lump sum regardless of your debts. Choosing the correct product is the first step toward finding the cheapest mortgage protection Ireland provides for your specific home-ownership needs.
Can I change my MORTGAGE PROTECTION provider after I have started my mortgage?
Yes, you have the right to switch your provider at any stage during your mortgage term. Many homeowners find they can secure a lower premium by moving from a bank-linked policy to an independent insurer. The process is straightforward and won’t affect your mortgage interest rate; your new provider simply issues an assignment to your lender to ensure the debt remains covered.
How much does the average MORTGAGE PROTECTION policy cost per month?
Monthly costs vary significantly based on individual factors like your age, health status, and the size of your loan. Premiums are calculated based on the risk of a claim during the term. Younger applicants and non-smokers generally access the most competitive rates. Since every profile is unique, a market-wide review is the only way to determine your specific monthly cost accurately.
What happens to my MORTGAGE PROTECTION if I decide to switch my mortgage lender?
You can usually keep your existing policy or use the transition as an opportunity to find a more affordable rate. If you choose to keep it, the policy is simply reassigned to your new lender. However, because your loan-to-value ratio has likely improved since you first bought your home, switching lenders is often the ideal time to hunt for a better insurance deal.
Do I need a medical exam to get the cheapest MORTGAGE PROTECTION rates?
Most applications are accepted based on a digital health questionnaire without the need for a physical exam. A medical assessment is typically only requested for very high cover amounts or if you disclose a pre-existing health condition. Providing meticulous and honest details during the initial application helps ensure your quote is finalised quickly and stays at the most competitive price possible.
Can I add CRITICAL ILLNESS INSURANCE to my MORTGAGE PROTECTION policy?
Yes, you can often add this as an optional benefit to your main policy. It provides a lump sum payment if you are diagnosed with a specified serious illness during the mortgage term. Whilst this addition will increase your monthly premium, it offers broader security by ensuring you can manage your debt or daily expenses if you’re unable to work due to health issues.
Why is a MORTGAGE BROKER often better than a bank for insurance?
A broker has access to a wide panel of insurers, whereas a bank is typically tied to just one provider. This independence allows a broker to compare the entire market to find the cheapest mortgage protection Ireland has available for your profile. They also act as a buffer against technical jargon, managing the underwriting process and paperwork to ensure a seamless and efficient experience.
What is the cheapest way for a smoker to get MORTGAGE PROTECTION?
The most effective way to lower your costs is to remain tobacco-free for at least 12 months, which allows you to apply for non-smoker rates. If you currently smoke, comparing quotes from multiple independent insurers is essential. Some providers have different appetites for smoking-related risks, so a comprehensive review is the only way to ensure you aren’t paying more than necessary for your cover.
Disclaimer
Engage Financial Services LTD T/A Engage Financial Solutions is regulated by the Central Bank of Ireland CRO 764570. Director David Moore. Suite 2 First Floor, 14 -18 Main street, Blackrock, Co Dublin A94 W0Y3