If you’re searching for an independent mortgage advisor Ireland, don’t assume the word “independent” means every lender or mortgage option is considered. That doesn’t make the support unsuitable, but it does mean you should understand what the service covers before deciding. Whether you’re comparing an adviser with applying directly to a lender or weighing up different advisers, ask which lenders are included, how the adviser is paid and whether any client charges could apply.
The right support depends on your circumstances, not just a label. Whether you’re buying your first home, switching your mortgage or exploring a Buy-to-Let Mortgage, ask which lenders are included, what the adviser can help with and how recommendations are tailored to your needs. This guide explains what independence can and can’t promise, sets out practical questions about lender access, commission and client charges, and helps you compare advice with a direct application. You’ll be better prepared to discuss your options without feeling under pressure to proceed.
Key Takeaways
- Ask what “independent” means in practice, including which lenders and mortgage options the adviser considers.
- Check the adviser’s current regulatory information, qualifications and written disclosures before deciding whether to proceed.
- Compare adviser support with contacting a lender directly, and ask how recommendations, commissions and any client charges are explained.
- Use the initial fact-find to discuss your goals, finances and mortgage needs, and clarify what happens at each stage.
- Engage Financial Solutions arranges mortgage loans from a panel of lenders. Ask which lenders and options are included to see whether its guidance fits your circumstances.
What does an independent mortgage adviser do for you?
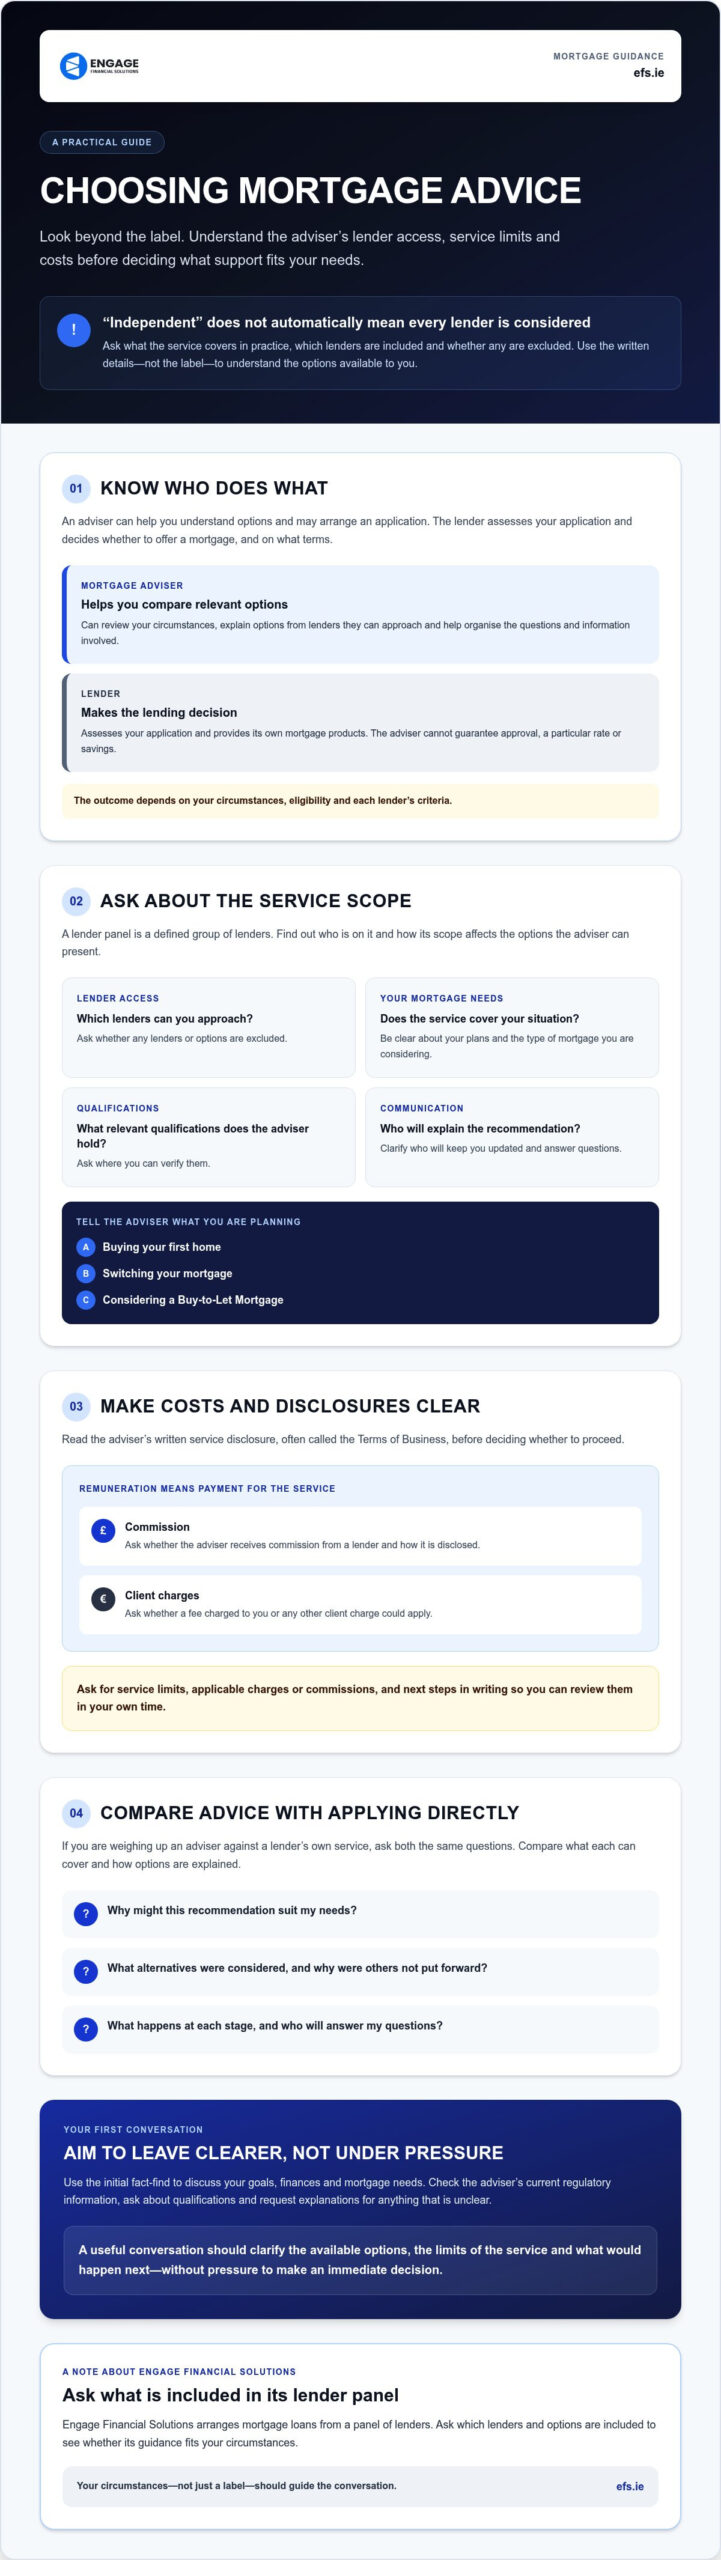
An independent mortgage adviser helps you understand mortgage options and may arrange an application with a lender. They can review your circumstances, explain how available options compare and help you consider what may fit your needs. They don’t provide the loan: the lender assesses your application and decides whether to offer a mortgage and on what terms.
How does an adviser differ from a lender?
A lender assesses applications and provides its own mortgage products. An adviser acts as an intermediary, helping you explain what you need and presenting relevant options from lenders they can approach. For a plain-English overview of this intermediary role, see What is a mortgage broker. An adviser’s recommendations can help you compare options, but the lender makes the lending decision.
What does independence mean in practice?
The word “independent” alone doesn’t confirm that an adviser considers every lender or product. Ask which lenders and mortgage options are included in the service, and whether any are excluded. If an adviser uses a lender panel, they work with a defined group of lenders. Ask who is on the panel and how its scope affects the options they can present.
Read the adviser’s written service disclosure, often called their Terms of Business, before deciding whether to proceed. It should explain what the service covers and how the adviser is paid. Remuneration means payment for the service, such as commission from a lender or a fee charged to you. Ask whether either applies, how any commission is disclosed and whether you could face a client charge. Use the written details, rather than the label, to judge the service.
Focus on the adviser’s actual scope. Check their current regulatory information and ask them to explain anything that isn’t clear. A useful first conversation should clarify the options available through that adviser, the limits of the service and what would happen next. You should be able to ask questions without pressure to make an immediate decision.
Which checks help you choose an independent mortgage adviser?
A useful first conversation should leave you clearer about the service, not simply reassured by the word “independent”. Before sharing documents or deciding to proceed, check whether the adviser understands your mortgage goal and can explain the limits of their service. If you’re comparing advice with a lender’s own service, ask both the same questions.
What should you ask about lender access and advice scope?
Ask which lenders the adviser can approach, whether any are excluded and which mortgage types the service covers. Be specific about your plans, such as buying your first home, switching your current mortgage or applying for a Buy-to-Let Mortgage. A general description of a lender panel doesn’t show whether the whole market is covered. Ask for enough detail to understand what may be missing.
Use this checklist to guide the conversation:
- Scope: Does the service cover your mortgage type and circumstances?
- Lender access: Which lenders can the adviser approach, and are any excluded?
- Qualifications: What relevant qualifications does the adviser hold, and where can you verify them?
- Communication: Who will explain the recommendation, keep you updated and answer questions?
If you’re switching, compare the adviser’s explanation with your priorities. Ask why a particular option may or may not suit you, and what alternatives were considered. The CCPC offers further background on understanding mortgage rules and options. You can also review the available Switching Mortgage information as part of your research.
How can you check credentials and service transparency?
Check the adviser’s current regulatory information and read their written service disclosure before engaging them. Confirm the details through relevant official information rather than relying on a verbal assurance or an unexplained badge. Ask for the service limitations, any applicable charges or commissions, and the next steps in writing so you can review them in your own time.
Ask how the adviser will explain a recommendation and why other options weren’t put forward. You should be able to follow the reasoning and raise concerns without feeling rushed. A transparent service makes clear what the adviser can consider, how they’re paid, why an option is recommended and what happens next.
If you’d like to explore whether tailored mortgage guidance may suit your plans, you can discuss your mortgage needs with Engage Financial Solutions before deciding whether to proceed.
Is an independent mortgage adviser always the right choice?
No. “Independent” doesn’t automatically mean an adviser covers every lender or mortgage option. The service’s actual scope matters, as does the kind of support you want. You might value help organising a more involved application, or prefer to speak directly with a lender about its own products. Neither route is automatically right for everyone.
Use this comparison to identify what you’ll want to check before choosing:
Scope
An adviser may consider options from the lenders they work with. Ask which lenders are included and whether your mortgage needs are covered. A lender can explain its own products, but not the wider market.
Support
An adviser may help organise your circumstances and explain relevant options. A lender can answer questions about its application process and products. Confirm what help each service includes.
Choice
An adviser’s options depend on the service and lender access. A direct approach focuses on one lender’s offering. Neither conversation alone tells you how the options compare with other available choices.
Information to verify
Check the adviser’s written disclosures, any limitations and how they’re paid. With a lender, review the product terms and the information provided about its offer.
When might adviser support be useful?
Guidance may be helpful if your needs involve several considerations, your circumstances have changed or you’re unfamiliar with the steps involved. For example, you could be buying your first home and checking whether a support scheme may be relevant. Citizens Information explains government schemes for homebuyers. Check the current details and whether you meet the criteria. An adviser may help organise mortgage options and application information, but can’t promise approval, a particular rate or savings.
When might you approach a lender directly?
If you want to understand a particular lender’s offering, contacting it directly may suit your preference. Before deciding, compare more than the initial conversation: look at the terms, the support provided and the options outside that lender’s range. If you’re also considering advice, ask the adviser the same questions about scope and support. A like-for-like comparison can help you choose with greater confidence. A search for “independent mortgage advisor Ireland” may bring up services with different lender access, so check the details instead of relying on the label.
Convenience, the complexity of your plans and how much guidance you want can all shape the best route for you. If you’re considering an independent mortgage advisor Ireland, weigh the adviser’s scope against your preferences and compare it fairly with approaching a lender directly. The aim isn’t to choose a label. It’s to understand what each option covers and decide which fits your circumstances.
What happens when you work with a mortgage adviser?
The process usually begins with a conversation about what you’re hoping to do, followed by a review of your circumstances and a discussion of possible mortgage options. The exact steps can vary between advisers and cases, so ask at the outset what the service includes and what you’ll need to provide.
What information might an adviser ask you for?
An initial fact-find is a discussion to understand your goals, finances and mortgage needs. You may be asked about your income, regular financial commitments, deposit and property plans, such as whether you’re buying your first home or switching an existing mortgage. These details help the adviser understand your situation and identify options that may be relevant. For those looking to review their wider household budget and long-term financial planning ahead of speaking with a lender, find out more through financial advisory specialists like Liknesh.
There isn’t one document list for every application. Requirements can vary, so ask what information is needed, how it will be collected and used, and how it will be kept secure. If you’re a first-time buyer, the First-Time Buyer Mortgage guide can provide further background on that route.
How are recommendations and applications explained?
Once the adviser understands your needs, they may present options available through their service and explain why each could be suitable, along with any trade-offs. Ask how the options compare with your priorities and what alternatives weren’t included. You should have time to consider the explanation and raise questions before deciding what to do next.
If you choose to proceed, the adviser may help organise the application information and explain what happens when it goes to a lender. The lender makes its own assessment and decides whether to approve an application. Its requirements depend on the lender and the details of your case, so an adviser can’t promise an outcome.
Keep the process clear and manageable. After each conversation, note the options discussed, any decisions you’ve made, questions still to ask and agreed next steps. This gives you a useful record and helps you keep track of important details.
- Before the fact-find: Write down your goal, such as buying a home or reviewing your current mortgage.
- During the discussion: Ask for unfamiliar terms or comparisons to be explained in plain language.
- Afterwards: Confirm who will take the next step and what information, if any, you need to provide.
If you’d like to discuss your circumstances and mortgage needs, speak with Engage Financial Solutions before deciding whether to proceed.
How can Engage Financial Solutions support your mortgage decision?
Once you’ve considered what you need from an adviser, compare those needs with the service on offer. Engage Financial Solutions provides personalised mortgage guidance and arranges residential and commercial loans from a panel of lenders. A panel is a group of lenders an adviser can approach, so its scope affects which options may be considered. Ask for details of the current panel rather than assuming it covers every lender.
Which mortgage needs can the team discuss?
Your plans help determine whether the service is relevant. Engage Financial Solutions lists support for Switching Mortgages, First-Time Buyer Mortgages, Buy-to-Let Mortgages and Self-Build Mortgages. The right option depends on your circumstances, mortgage needs and eligibility, as well as the criteria of lenders available through the panel. These arrangements are not a promise of approval or a particular outcome.
Before deciding, explain what you’re hoping to do and ask whether the team’s service covers your situation. You could ask which lenders and mortgage options may be relevant, what falls outside the service, and how any recommendation will be explained. This helps you assess whether the guidance fits your needs, whether you’re buying, switching or considering a property for rental.
What should you confirm before taking the next step?
Ask for the current lender-panel scope and any service limitations in writing. Check how the adviser will document recommendations and explain why other options weren’t included. Before proceeding, request written disclosures that set out how the adviser is paid, including whether lender commission or a client charge applies. Also check the business’s current regulatory disclosure and verify its details through relevant official information.
Engage Financial Solutions is regulated by the Central Bank of Ireland. Check the current regulatory disclosure and ask the team to clarify any detail you’re unsure about. A conversation can help you understand whether the service suits your plans without committing you to proceed.
If you’d like to talk through your circumstances and mortgage options, Discuss your mortgage needs with Engage Financial Solutions.
Choose support that fits your next move
The right mortgage support depends on more than the word “independent”. Check which lenders and options an adviser can consider, how the service is paid for and whether the adviser understands your plans. If you’re searching for an independent mortgage advisor Ireland, use these practical checks to compare advice with speaking directly to a lender.
Engage Financial Solutions provides personalised mortgage guidance and arranges loans from a panel of lenders. Before proceeding, ask about the panel’s current scope, service limitations and how recommendations will be explained. The business is regulated by the Central Bank of Ireland. Check its current regulatory disclosure and clarify any client charges and lender commissions in the written service information.
Whether you’re considering Switching Mortgages or another step, an initial discussion can help you assess whether the service fits your circumstances. If you’re still comparing options for an independent mortgage advisor Ireland, take time to ask your questions and review the answers before deciding. Discuss your mortgage needs with Engage Financial Solutions to explore whether its service suits your plans.
Frequently Asked Questions
What does an independent mortgage adviser do?
An independent mortgage adviser helps you review your circumstances and consider mortgage options available through their service. They can explain differences, discuss how options may fit your needs and may arrange an application with a lender. The adviser doesn’t provide the loan or decide whether to approve you. Ask which lenders and mortgage types they can consider, as “independent” doesn’t automatically mean the whole market is covered.
Is an independent mortgage adviser better than going directly to a bank?
Neither route is automatically better. The right choice depends on the support and range of options you want. An adviser may help organise comparisons across the lenders they work with, while a bank can explain its own mortgage products directly. Compare the service scope, terms, available options and any charges before choosing. If you speak with both, ask the same questions to make the comparison fair.
How much does an independent mortgage adviser charge?
Charges depend on the adviser’s payment arrangements, so ask for the current details in writing before proceeding. An adviser may receive commission from a lender, charge a client fee or use different arrangements for different cases. Engage Financial Solutions arranges mortgages in exchange for lender commissions or flat client engagement fees. Confirm whether a client charge applies to you, how commission is disclosed and what the service includes.
Can an independent mortgage adviser access every lender?
No. The word “independent” doesn’t by itself confirm access to every lender. An adviser may arrange loans through a panel, meaning a defined group of lenders they work with. Ask which lenders are currently included, whether any are excluded and how this affects the options they can present. A broad description of a panel isn’t proof of whole-market access, so request clear written information about its scope.
What should I bring to my first mortgage adviser meeting?
Start with a clear outline of your plans and finances, rather than assuming a particular document list applies. Be ready to discuss income, regular commitments, your deposit and the type of property or mortgage you’re considering. Requirements vary with the lender and your circumstances, so ask the adviser in advance what information would be useful. Also ask how your details will be collected, used and kept secure.
Can a mortgage adviser guarantee mortgage approval?
No. An adviser can’t guarantee that a lender will approve your application. The adviser may help you understand options and organise information, but the lender carries out its own assessment and makes the decision. Approval and any offer depend on your circumstances and the lender’s criteria. Treat promises of guaranteed approval cautiously, and ask the adviser to explain what is known, what remains uncertain and what the next steps involve.
How do I know whether a mortgage adviser is regulated?
Check the adviser’s current regulatory information and written disclosures, then verify the details through official Central Bank information. Make sure the name and status match the adviser or business you’re considering, and ask for clarification if anything is unclear. Engage Financial Solutions is regulated by the Central Bank of Ireland. Check its current regulatory disclosure and read the service terms, including lender access and payment arrangements.
Disclaimer
Engage Financial Services LTD T/A Engage Financial Solutions is regulated by the Central Bank of Ireland CRO 764570. Suite 2 First Floor, 14 -18 Main street, Blackrock, Co Dublin. A94 W0Y3